
Case study
Flick
There wasn’t a single screen in Figma.
- Client
- Flick
- Timeline
- Jan 2023 – Dec 2025
- Industry
- Fintech, Open banking
- Role
- Lead product designer, with one junior designer
- Platform
- Web dashboard + marketing site
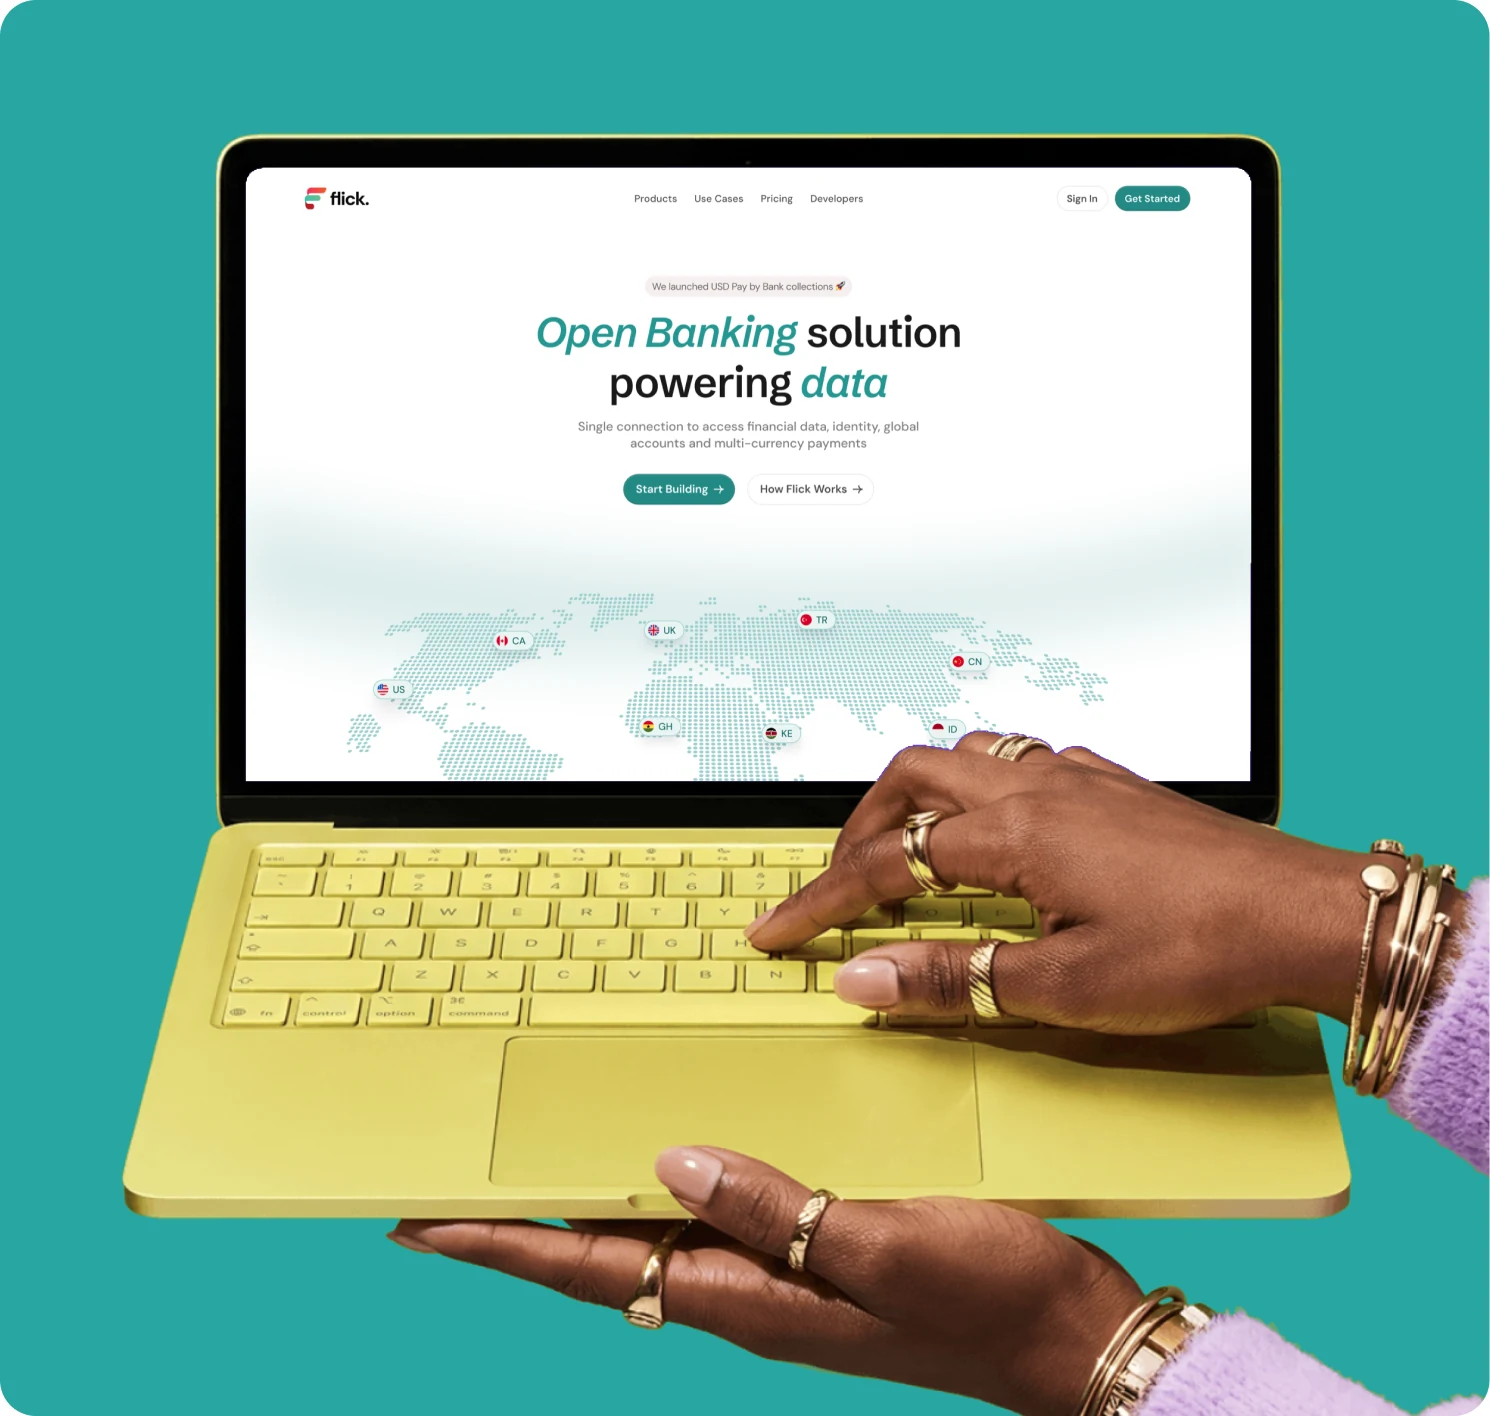
When I joined Flick, the product was a founder-built app that kept breaking. I audited everything, then led design on the merchant dashboard Flick launched and still runs on: one place for businesses to move money, see their data and verify their customers.
The short version
From a breaking app to the dashboard Flick runs on.
No design files, no system, and a founder-built app that broke under real use.
Audited the product, then led design on the merchant dashboard end to end: sign-up, balances, payments, customer data and credit reports.
Launched to 12+ active businesses in the first month, with 25% sign-up conversion and 70% 30-day retention.
Where it started
There was no design to start from.
Flick is an open banking platform. Businesses use it to collect payments, pay out across currencies, and pull financial data and identity checks on their own customers.
When I joined, the founder had built the first version in code. It worked until it didn’t, and there were no Figma files, no components and no shared picture of what the product should be. So the first job was understanding what was already there.
The audit
First, find out what’s actually broken.
“Collections” and “Payout” were our words. Merchants think in money in and money out, so they became Inflow and Outflow.
Moving money, the thing merchants do most, was buried. It became one Move money button at the top of every page.
Sign-up sent people to their inbox to click a link. It became a one-time code, with deeper KYB checks once you’re in.
Swipe to follow the whole flow, pinch to zoom in

How merchants use it
Sign up, move money, know your customers.
Sign-up asks for four things (business name, type, website and country) and a one-time code. Full KYB comes later, when it’s needed. Inside, balances in every currency sit up front with Move money one click away, and each customer’s linked accounts, identity, statements and credit reports live in one place.
Decision 01
Show the money first.
When merchants log in, they want to know how much they have and where. The overview leads with balances per currency, each one clickable, then transactions over time. Businesses using Flick for data get their own view (API wallet, usage and errors) behind a simple Payments / Data switch.
Tradeoff
Two kinds of merchants, one product. A switch kept both views simple instead of cramming payments and data onto one screen.


Decision 02
One customer, one page.
Flick sells accounts, identity, transactions, statements and credit reports. Before, each lived in its own corner. I brought them together on a single customer profile with tabs, so a lender looking at a business sees linked bank accounts, inflows, identity and credit history without leaving the page.
Tradeoff
More tabs on one page, but nobody has to piece a customer together from five different screens.

Decision 03
Speak the merchant’s language.
Some of the audit’s fixes were small. Recurring PayLinks became Direct Debit, and sign-up sends a code instead of a link.
Tradeoff
Renaming core features meant updating the docs and support material, but the product now uses the words merchants already use.
Outcome
12+ businesses, 25% conversion, 70% retention.
The dashboard launched with 12+ businesses active in the first month. 25% of sign-ups converted, and 70% were still active 30 days later.
In the first quarter after launch, Flick’s overall revenue grew by 30%. The real-time dashboard and automated recurring payments were the most-used features. Some flows weren’t as smooth as designed, so I worked back through them with engineering and we fixed them quickly.

What I’d do differently
Plan the metrics with the design.
We measured activation, conversion and retention after launch. Next time I’d agree on them with the team before design starts, and add time to first transaction, the moment a merchant starts to trust the product.
 Pesa